What the Tampa court calendar looks like
A foreclosure in Hillsborough County moves through the local circuit court. The lender files, you are served, and the case follows the docket. The courthouse and the auction schedule are local, and that matters when you are counting days. The process usually takes six to twelve months from the first missed payment to the final sale.
The clerk handles the public sale after final judgment. The sale is usually set a few weeks out. If you are going to sell, the closing has to happen before the clerk records the sale. I start with the docket date, not with a sales pitch, because the date decides whether a sale is realistic.
Before the lawsuit, the lender sends a default notice. Gather your mortgage statements, property tax records, homeowner insurance information, and any letters from the lender. Those documents make the payoff and the timeline easier to pin down, and they keep the servicer letter from becoming your only calendar.
Why the buyer matters more than the list price
A retail buyer in Tampa can pay more, but that buyer needs a loan, an appraisal, and an insurance policy. If the roof is old or the house has an open permit, the lender may not approve the loan. A cash buyer does not need a lender, but the buyer still needs a clean title and enough time to close.
I have seen sellers accept a higher offer from a financed buyer and lose the house anyway when the loan fell through. I have also seen sellers take a lower cash number and close in time. The right comparison is not the headline price. It is the price you actually receive before the auction date.
A cash buyer should show proof of funds and name the title company before you sign. If the buyer cannot do either, the closing date is a guess. In a foreclosure, a guess is expensive.
A local buyer should also know the difference between a clean payoff and a moving target. If the servicer adds fees or the escrow changes, the number at closing can move. Ask for a payoff good through the closing date, and have the title company confirm it the day before.
Short sale, reinstatement, or deed in lieu
A short sale asks the lender to accept less than the payoff. It can be the right path when the house is worth less than the loan, but it needs lender approval and it takes time. A reinstatement means paying the past due amount. A deed in lieu transfers the house to the lender, which still affects your credit and usually leaves you with nothing from the sale.
None of these are quick fixes. If you have equity and a clean title, a sale can pay the loan and leave something for you. If you do not, the lender has to be part of the conversation. I will not pretend a cash offer can erase a payoff problem that the numbers do not support.
A loan modification or forbearance can also change the timeline, but approval is not guaranteed. If the lender offers a trial payment plan, read the terms before you skip a sale opportunity. A plan that fails near the auction date leaves less room than you had before.
The house conditions I see in Tampa
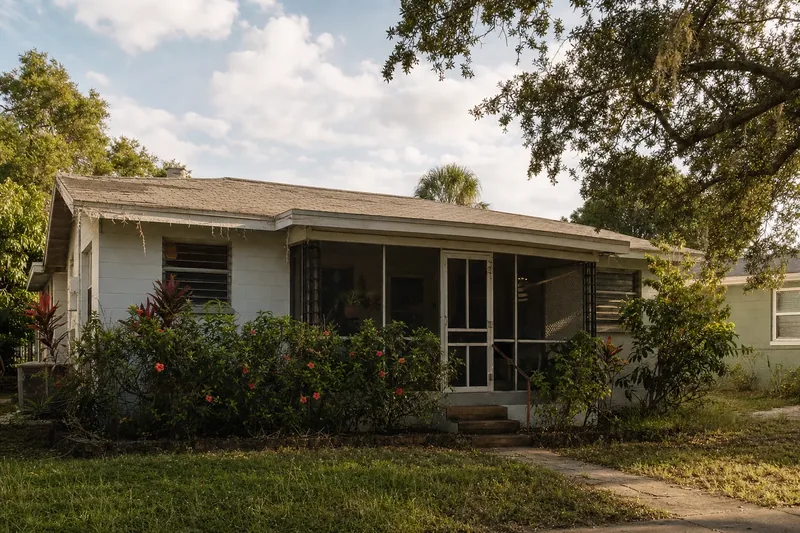
In Seminole Heights, 1950s block bungalows often have screened porches, later additions, and worn shingle roofs. Those are the housing stock details that change the repair budget. In the rest of Tampa, the roof, the plumbing, and the electrical panel matter more than the style of the house.
I look at the roof, the ceiling stains, the electrical panel, the plumbing, and the lot. I also ask who lives there and whether the house is empty. Storm or water damage, an older roof, or a tenant problem can limit the pool of financed buyers. That is a repair and financing cost, not a moral judgment.
The condition does not have to be pretty. It has to be honest. If the roof is at the end of its life or work was done without a permit, say so on the first call. I would rather bring the right contractor than discover it at the door.
I also look at the lot. A house in a flood zone can carry insurance costs that a financed buyer will notice. A house on a busy road can be harder to sell. Those are not reasons to give up. They are reasons the price and the buyer pool change.
A plain next step
Call me with the address and the auction date if you have one. I will tell you whether the timing is realistic. If it is, we can walk the house, open title, and work toward a closing at a local title company. If it is not, I will tell you what has to happen first.
The decision is easier when you have the dates, the payoff, and the condition in front of you. Bring the paperwork to the table. I will bring a calculator and a straight answer. You can also read how we handle foreclosure sales before we talk.
You still have choices, even after the case is filed. The sooner you put the real dates on paper, the more of them you keep.
If the case is already at final judgment, keep the title company in the conversation. A title company can tell you what it needs for a clean closing before you accept an offer. That call is free and it can save the deal.
Sources
- The Hillsborough County Clerk of Court lists the local foreclosure sales, so the clerk is the place to confirm the auction date. the Hillsborough County Clerk of Court
- Florida Statutes section 45.031 sets the judicial sale procedure, including the 20 to 35 day window between the final judgment and the clerk's public sale.
- USA.gov lists the housing counselors and free foreclosure help that can run alongside a Tampa case. USA.gov foreclosure help
Frequently asked questions
Can I sell my Tampa house after the foreclosure auction is scheduled?
Sometimes. The sale can still close if the payoff reaches the lender and the clerk does not record the sale first. That takes a clean title and a buyer who can close without a mortgage. If the auction is days away, ask a title company whether the file can be completed in time. A promise from a buyer is not a date.
How long does a foreclosure take in Hillsborough County?
The case usually runs six to twelve months from the first missed payment to the final sale, and the exact pace depends on the court and the lender. The 120 day pre-foreclosure window comes first. After a final judgment, the clerk sets the auction, often a few weeks later. The docket is the schedule that matters.
Is a short sale better than a cash sale in Tampa?
It depends on the payoff and the lender. A short sale can reduce the loss when the house is worth less than the loan, but it needs lender approval and it takes time. A cash sale can close faster, but it cannot solve a payoff that is higher than the house value. Ask an attorney or a HUD approved counselor to compare them.
Do I need to make repairs before selling in foreclosure?
No, if you sell to a buyer who accepts the house as is. The repairs are priced into the offer instead of becoming a repair request. You still disclose known problems, and the buyer still walks the property. A rough house can close. A title problem is what stops a closing.