St. Petersburg, FL(727) 291-9712·Open 24 hours
mortgage payoff options

Selling a Florida house that still has a mortgage

You can sell a house in Tampa Bay even if the mortgage is not paid off. The real question is whether the sale price covers the payoff and costs, or whether you need a lender approved short sale.

Quick answer

Yes. A mortgage usually gets paid from closing proceeds, but you need the payoff letter, a clear look at closing costs, and a plan if the loan balance is higher than the home value. In that case, a short sale or another lender workout may be the practical path.

  • Request the payoff letter
  • Check equity after costs
  • Short sale may help
  • Attorney review is wise

No repairs, no cleanout, no agent commission. You do not have to accept the offer.

Selling a Florida house that still has a mortgage
The payoff comes out of the sale at closing, like any other closing.
Where you are right now

What you are dealing with

You need a plain answer about payoff, timing, and what happens if the numbers are tight. A house with a mortgage is not unusual. What makes it stressful is not knowing whether there will be enough money at closing to pay the lender and still let you move on.

The first practical step is getting a formal payoff letter and understanding how closing costs affect your net proceeds. If you owe more than the home is worth, the next question is whether a short sale is possible and whether the lender will approve it.

In Florida, possible paths may include catching up or working out a plan with your servicer, selling traditionally if your home has equity, or a lender approved short sale if it does not. A short sale can often move faster than foreclosure with the right representation.

What you are dealing with
The letter arrives, and the decisions start before anyone has had time to think.

How this usually plays out

Most owners with a mortgage move through the same few decision points. The pace depends on payoff information, equity, title, and whether the lender must approve a short sale.

  1. first

    check the payoff

    Start by requesting a formal payoff letter from the loan servicer. That gives you the amount needed to satisfy the mortgage and helps show whether a normal sale is realistic.

  2. next

    compare value and costs

    Then compare likely sale proceeds against the payoff and closing costs. This is where owners learn whether they have equity, are close to even, or may need lender approval.

  3. after that

    choose the sale path

    If there is equity, you can usually list or sell directly. If there is not, a lender approved short sale may be the better path. Ask a Florida attorney to review the payoff side.

  4. if pressure is building

    watch the longer risk

    If payments are not current, remember that foreclosure in Florida can take 12 to 18 months, while a short sale can often be completed in 3 to 6 months.

  5. last

    close and pay the loan

    At closing, the title company uses sale proceeds to pay the mortgage according to the payoff letter. If the file is straightforward, our closings are typically about 2 weeks.

How this usually plays out
Most owners are somewhere on this path already, often further along than they realise.

Need the plain version

We can review the house and discuss payoff without any pressure.

Talk it through
Your honest options

Your main options

These are the usual paths when a Florida house still has a mortgage.

Your main options
There are usually three or four real paths, and no single one fits everyone.

Wait or do nothing

What it is
Keep the house for now and make no sale decision yet.
What helps
Buys time if income or family plans may improve soon.
What to weigh
Interest, payments, and stress can keep building in background.

Best fitMay be better if the loan is current and time helps.

Sell with an agent

What it is
List the home and try for the highest market price.
What helps
Best chance to preserve equity when condition and access are solid.
What to weigh
Showings, repairs, timing, and financing can complicate payoff planning. An FHA buyer also adds about 10 days to the closing timeline compared with a conventional buyer, which matters if your payoff date is tight.

Best fitA better fit when you have equity and can prepare.

Short sale or payoff

What it is
Use sale proceeds to pay lender, or seek lender approval.
What helps
Directly addresses the mortgage problem and can avoid longer foreclosure.
What to weigh
Approval, documents, and lender review can slow the process.

Best fitMay be better when value is below the loan balance.

Sell to a cash buyer

What it is
Sell as-is directly and use closing proceeds toward the mortgage.
What helps
Simple process, no repairs, no cleanout, and no agent commission.
What to weigh
Price may be lower than a strong retail sale.

Best fitCash is the right choice for some sellers who want simplicity.

Compare your choices

Ask for a cash offer if you want one more concrete option.

See our offer
What we do and why

How we help when there is still a mortgage

We start with the facts, not a pitch. That means the property address, who is on title, the mortgage servicer, and whether the loan is current. If you already have a payoff letter, we review that too.

Then we walk the house in its current condition. We buy as-is, so you do not need to repair, clean out, or get the place ready for showings. Older homes, condos, coastal properties, and dated interiors are all normal for us.

If the numbers work, we make a cash offer and open title. The title company reviews ownership, liens, and the mortgage payoff. If a short sale may be needed, we will say that plainly and suggest you speak with a Florida attorney about approval.

  • We review payoff and title basics
  • We buy houses in as-is condition
  • No repairs or cleanout required
  • No agent commission or fees
  • You decide if it fits
How we help when there is still a mortgage
We price the house in its current condition, not the version it could be with repairs.
The process

Our five step process

  1. Talk through the mortgage

    We ask about the loan, payment status, property condition, and whether you already requested a formal payoff letter.

    You need
    • property address
    • owner names
    • mortgage servicer info
  2. Walk the property

    We visit the house, note condition, and discuss any access issues, tenants, contents, or repairs you do not want to handle.

    You need
    • basic access
    • recent photos
    • occupancy details
  3. Make a clear offer

    If it fits our model, we make a cash offer and explain it plainly so you can compare it with other options.

    You need
    • sale goals
    • timing preference
    • payoff estimate
  4. Open title review

    A local title company checks ownership, liens, and the mortgage payoff so the closing statement reflects the real file.

    You need
    • photo identification
    • loan statement
    • mailing address
  5. Close and pay lender

    At closing, the title company pays the mortgage from proceeds and handles the documents needed to complete the transfer.

    You need
    • signing availability
    • forwarding details
    • house keys
Our five step process
A clean handover is the goal: keys, paperwork, and a date both sides can plan around.

Simple next step

Send the address and we will explain what we need first.

Start here
Local

Tampa Bay context matters

Mortgage payoff questions look different depending on the house and county. In Tampa Bay, owners may be dealing with older roofs, flood exposure, condos, inherited upkeep, or a house that simply did not keep pace with the loan balance.

We buy across the region and adjust to the local facts. That includes title issues, property condition, access, and whether a listed sale, short sale, or direct sale makes the most sense.

Tampa Bay context matters
A short, straightforward conversation is usually enough to know which path makes sense.

Pinellas

St. Petersburg to Clearwater often means older homes, condos, and coastal exposure.

Hillsborough

Tampa area owners may weigh equity, servicer plans, listing, or short sale.

Manatee

Bradenton area homes range from coastal properties to newer inland subdivisions.

Proof

A simpler sale when life was already complicated

Case study

One seller was leaving the country and did not want repairs, renovations, showings, or open houses. We walked the property, made a cash offer, opened title review, and closed at a local title company. He said the price was better than most competing offers, and that the process was smooth, professionally handled, and very convenient during a disruptive time.

“They offered a better price than the majority of the competition”

Andy Bentley, Google review

As-is sale, clear process, and no repair or showing burden.

They gave us a fair and competitive price for our property as opposed to other companies we were working with.
Michael McBride, Google review
They gave me a close date, and we closed on that very day.
Lisa Myers, Google review
The process was seamless and we closed within a month.
Randy Kahle, Google review
A short walkthrough, from our channel

Sell My House Fast

This short video is a plain walkthrough from our YouTube channel, not a customer testimonial. It introduces how we buy houses for cash around Tampa Bay, what the walkthrough covers, and how closing works, so a seller can see the process before requesting an offer.

A short walkthrough from our YouTube channel, not a customer testimonial.

Sell My House Fast
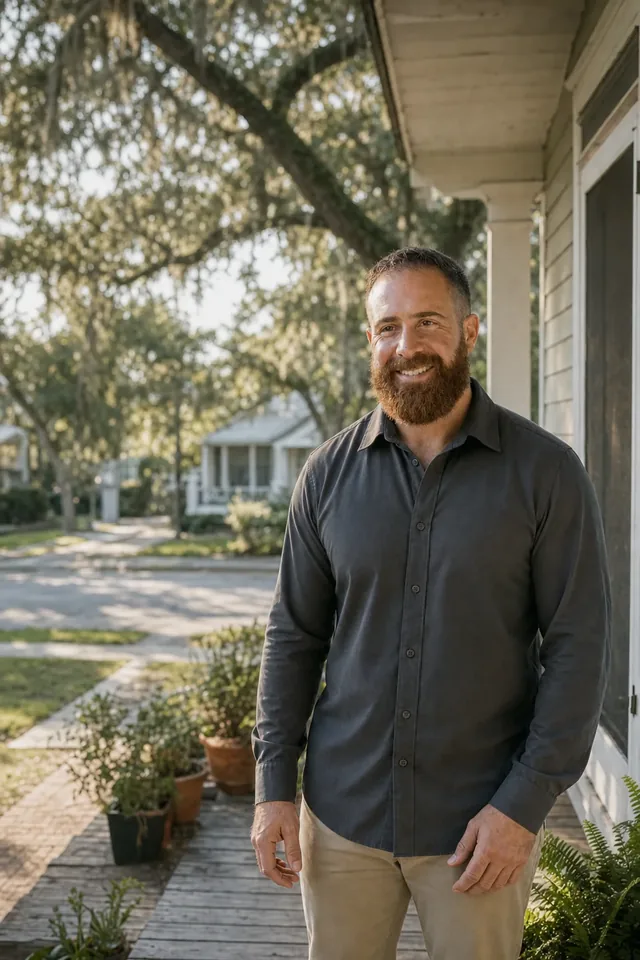
John Gardepe, co-founder of The Best Cash Home Buyer, on a walkthrough
John Gardepe, co-founder, on a walkthrough in St. Petersburg.
My background

Why John writes these pages

I am John Gardepe, co-founder of The Best Cash Home Buyer in St. Petersburg. For years, our team has bought houses across Tampa Bay. A lot of those calls start the same way. Someone still has a mortgage and wants a straight answer.

Most people are not asking for a speech about real estate. They want to know whether the sale can pay off the loan, whether a short sale might be needed, and how much work the process will put back on them.

That is why I try to keep these pages plain. We can buy for cash, as-is, with no repairs, no cleanout, no agent commission, no fees, and no obligation. But a direct sale is only one option, not the answer for every owner.

John Gardepe, co-founder

FAQ

Common questions

Can I sell my Florida house if I still have a mortgage?

Yes. In most normal sales, the mortgage is paid off from closing proceeds through the title company. The important part is getting a formal payoff letter and comparing that amount with the expected sale price and closing costs before you commit.

What if I owe more than the house is worth?

Then a regular payoff may not work, and a short sale or another lender workout may need to be explored. The key steps are understanding the payoff, the closing costs, and the lender approval path. A Florida attorney should review any short sale approval issues.

How do I find out my exact mortgage payoff amount?

Request a formal payoff letter from your loan servicer. That document is more useful than a rough online balance because it is prepared for closing. It helps the title company calculate what must be paid and whether the sale proceeds are likely to cover it.

Do closing costs matter if I am just trying to pay off the loan?

Yes, they matter a lot because they affect your net proceeds. A house may appear to have enough value at first glance, then look tighter once normal closing costs are included. That is why payoff review should happen before you choose a sale path.

Is a short sale faster than foreclosure in Florida?

It can be, but approval is the constraint rather than the calendar. A short sale needs the lender to accept less than the payoff, which means a package, a valuation and a negotiator's decision on their schedule. Ask the servicer what their current package requires before you assume the timelines will hold.

Should I keep making payments while I try to sell?

If you can, staying current usually gives you more room to choose among options. If that is not realistic, speak with your servicer about possible plans and ask a Florida attorney to review the payoff and any short sale approval questions before deadlines tighten.

Can I sell to a cash buyer and still pay off my mortgage?

Yes, if the sale price and net proceeds are enough to satisfy the payoff, or if the lender approves a short sale. In a direct sale, the title company still handles the mortgage payoff at closing. The difference is usually speed and less prep work.

How fast can you close if my house still has a mortgage?

When title is clear, closing is typically about 2 weeks on our side. The actual timing still depends on access, title work, and getting accurate payoff information from the lender. If a short sale is needed, the lender approval process can extend that timeline.

Do I need to make repairs or clean out the house first?

No, not for us. We buy as-is, which means you do not need to repair the property, empty it, or get it ready for showings. We still need enough access to walk the house and enough information to review title and payoff details.

Is listing with an agent better if I have equity?

Sometimes, yes. If the house shows well, the equity is real after costs, and you can handle showings and buyer financing, listing may be the better fit. A direct buyer is usually more useful when condition, timing, or uncertainty makes the retail path harder.
Ready for a straight answer

Call or message us and we will review the mortgage situation calmly.

Contact us
A calmer next step

You do not need to guess

If your Florida house still has a mortgage, the next step is not panic. It is getting the payoff, checking the real net, and comparing the honest options. We can give you a direct offer, or help you see that another path fits better.

Get My Free Cash Offer